
Your Money Needs a Home: Creating a Financial System That Works for Real Life
Money can become stressful surprisingly quickly when you don't have a clear picture of where it is going. You can pay your bills on time, work hard, and generally consider yourself responsible with money while still finding yourself wondering whether you can comfortably afford something, whether you've forgotten about an upcoming expense, or how much of the money in your account is actually available to spend.
I've learned that financial organization doesn't have to mean tracking every penny or creating a rigid budget that leaves no room for real life. For me, it has been much more about creating enough structure that I understand my financial situation and can make decisions without constantly second-guessing myself. In many ways, I think of it the same way I think about organizing a home: when everything is scattered around, it takes more mental energy to figure out what you have and where it belongs. When things have a place, life becomes a little easier.
The same principle can apply to money.
Organization Doesn't Have to Mean Rigidity
When people hear the word budget, they sometimes picture a system where every dollar has been assigned to a specific category before the month even begins. While that approach can work well for some people, I've never wanted my finances to become so rigid that I feel like I'm constantly monitoring myself.
What I value much more is having a clear enough picture of my income and expenses to recognize when I'm getting close to my limits. Because my income isn't exactly the same every month, knowing my basic expenses is especially important. I know what I need to bring in to cover the essentials without having to pull money from savings, which gives me a practical income goal to work toward each month.
That doesn't mean I can't spend money on something unexpected or enjoyable. It simply means I have enough information to understand the financial tradeoff before I make the decision. There is a lot more freedom in that kind of awareness than there is in either extreme of completely ignoring your finances or trying to control every dollar with absolute precision.
A financial system should provide structure without making your life feel smaller.
Giving Different Savings Goals Their Own Place
One of the ways I've created more clarity is by separating my savings according to what the money is intended to do. Rather than keeping everything in one large savings account and trying to remember which portion is meant for what, I have separate accounts for short-term savings, longer-term emergency savings, annual expenses, and quarterly taxes.
That doesn't mean I think everyone needs to have exactly the same accounts. The important part is understanding that savings can have different purposes, and separating those purposes can make it much easier to know what money is actually available.
If I have money set aside for an annual expense, I don't have to wonder whether spending it on something else is really okay. I already know that money has another job to do. Likewise, when I have extra income available, I can look at my different savings accounts and recognize which areas may need to be replenished rather than simply seeing one large balance and assuming all of it is available.
This has also helped me become more intentional about larger purchases. When your savings exists as one big lump sum, it can be tempting to look at the total and think you have more available than you actually do. Separating your savings can provide a much more realistic picture of what you can comfortably spend without leaving yourself unprepared for something else later.
Knowing Your Numbers Creates Breathing Room
You don't have to think about your finances constantly in order to be financially organized. In fact, one of the benefits of having a system is that you don't have to make the same decisions over and over again.
I know what my basic monthly bills are, what expenses are coming up, and roughly what I can expect my financial obligations to look like in the month ahead. That knowledge makes it much easier to recognize when something is simply an enjoyable purchase and when it would actually stretch me beyond what feels financially comfortable.
There's an important difference between spending money because you know you have room for it and spending money while hoping you haven't forgotten about something else. The first allows you to make a choice with confidence. The second can leave you with that nagging feeling that you've created a problem for your future self.
Having a financial system doesn't eliminate every difficult financial decision, but it can make those decisions much clearer.
Not Every “Unexpected” Expense Is Actually Unexpected
Another part of creating financial stability is learning to distinguish between expenses that are genuinely unexpected and expenses that are simply irregular.
An annual bill might not come every month, but if you know it is coming, it doesn't really need to be a financial surprise. The same can be true of vehicle maintenance, certain insurance payments, professional expenses, gifts, home repairs, or other costs that occur periodically.
This is where sinking funds can be so useful. Instead of waiting until the expense arrives and then trying to find the money for it, you gradually set money aside ahead of time. When the bill finally comes, you're not scrambling to figure out how to fit it into that month's budget because you've already been preparing for it.
That kind of preparation can change the way an expense feels. The amount of money required hasn't necessarily changed, but your experience of paying it can be completely different when you've already accounted for it.
You Don't Have to Earn More Before You Get Organized
I would also love to see more people let go of the idea that financial organization is something you can only worry about once you're making enough money.
Income obviously matters. If your necessary expenses consistently exceed what you earn, there is a real mathematical problem that organization alone cannot solve. But having a limited income and being disorganized with money are two different things, and earning more doesn't automatically teach someone how to manage what they have.
You can begin by getting a clearer picture of your current situation. Understanding your essential expenses, recognizing which bills come up throughout the year, identifying the things you're saving for, and knowing what money is actually available to spend can give you information that you can use regardless of your income level.
That clarity may also show you where you need to make changes. Perhaps you need to increase your income, reduce certain expenses, build your emergency savings, or change how you're allocating the money that comes in. Those decisions become much easier to make when you're working from an accurate picture instead of a vague sense that your finances are somehow not working.
Your System Has to Fit Your Real Life
There isn't one perfect financial system that will work for everyone. Someone with a steady salary may organize their money differently from someone whose income changes from month to month. A single person may have very different priorities from a parent, a homeowner, someone paying off debt, or someone preparing for a major life transition.
The goal isn't to find the system that looks the most impressive on paper. It is to create one that you can realistically maintain and that helps you make better decisions in the context of your own life.
For me, that means having enough organization to manage inconsistent income without feeling like every month is a guessing game. It means knowing my minimum expenses, preparing for recurring annual costs, keeping emergency savings separate, and paying attention to where my different savings accounts stand. Someone else's system may look completely different, and that's okay.
A useful financial system should make your life easier to manage, not become another source of stress.
Financial Organization Is About More Than Getting Through the Month
One of the things I've come to appreciate most about financial organization is that it isn't only about making sure the bills get paid. It gives you information that can help you make decisions about the future.
For example, larger financial goals can feel much more attainable when you understand your current position. Buying a home, building an emergency fund, changing careers, paying off debt, or working toward another major goal all require you to know where you are starting from and what you need to do to get where you want to go.
I've become especially aware of this through the process of understanding my own financial goals. Things like income, savings, credit, and monthly obligations aren't isolated pieces of information. They all affect what kinds of choices are available to you.
The more familiar you become with your own financial situation, the less intimidating those larger decisions can feel. You may not be able to make every goal happen immediately, but you can begin to see what needs to change and what steps will move you in that direction.
Creating a Financial Life That Supports You
I didn't always have the level of organization I have now. Earlier in my adult life, money was more of a matter of addressing things as they came up. I was always responsible about paying my own bills, but during my marriage, missed due dates and inconsistent financial management sometimes created unnecessary chaos in our shared finances.
That experience helped me understand how much financial organization matters. It also taught me that being responsible with money isn't just about remembering to pay the bills. It's about understanding your financial situation well enough to protect your future, recognize your limits, and make decisions intentionally.
Over time, I've found that this kind of organization has made me feel calmer and more confident. I don't need to know exactly what every month will bring in order to have a plan. I can look at where I am, see what needs attention, and make adjustments as my circumstances change.
That, to me, is what financial peace actually looks like. It isn't having a perfect financial life or reaching a point where nothing unexpected ever happens. It's having enough clarity and preparation that you can respond to what happens without feeling like everything is falling apart.
Your money doesn't have to be perfectly organized, and you don't need to create a complicated system that requires hours of maintenance. But giving your money some structure can help you understand what you have, what you need, and what you're working toward.
Maybe that means creating a separate place for emergency savings. Maybe it means starting a sinking fund for an expense that always seems to catch you off guard. Maybe it means figuring out your true monthly baseline so you know what you need to earn before you start thinking about everything beyond the essentials.
You can start wherever you are.
The goal isn't to become perfect with money. It's to become familiar with it.
When you understand your own financial landscape, you can make decisions from a place of greater clarity instead of constantly reacting to whatever comes next. And over time, that clarity can give you something that is worth much more than a perfectly balanced budget: the confidence to use your money intentionally as you build the life you actually want to live.
Create Your Own Financial Peace
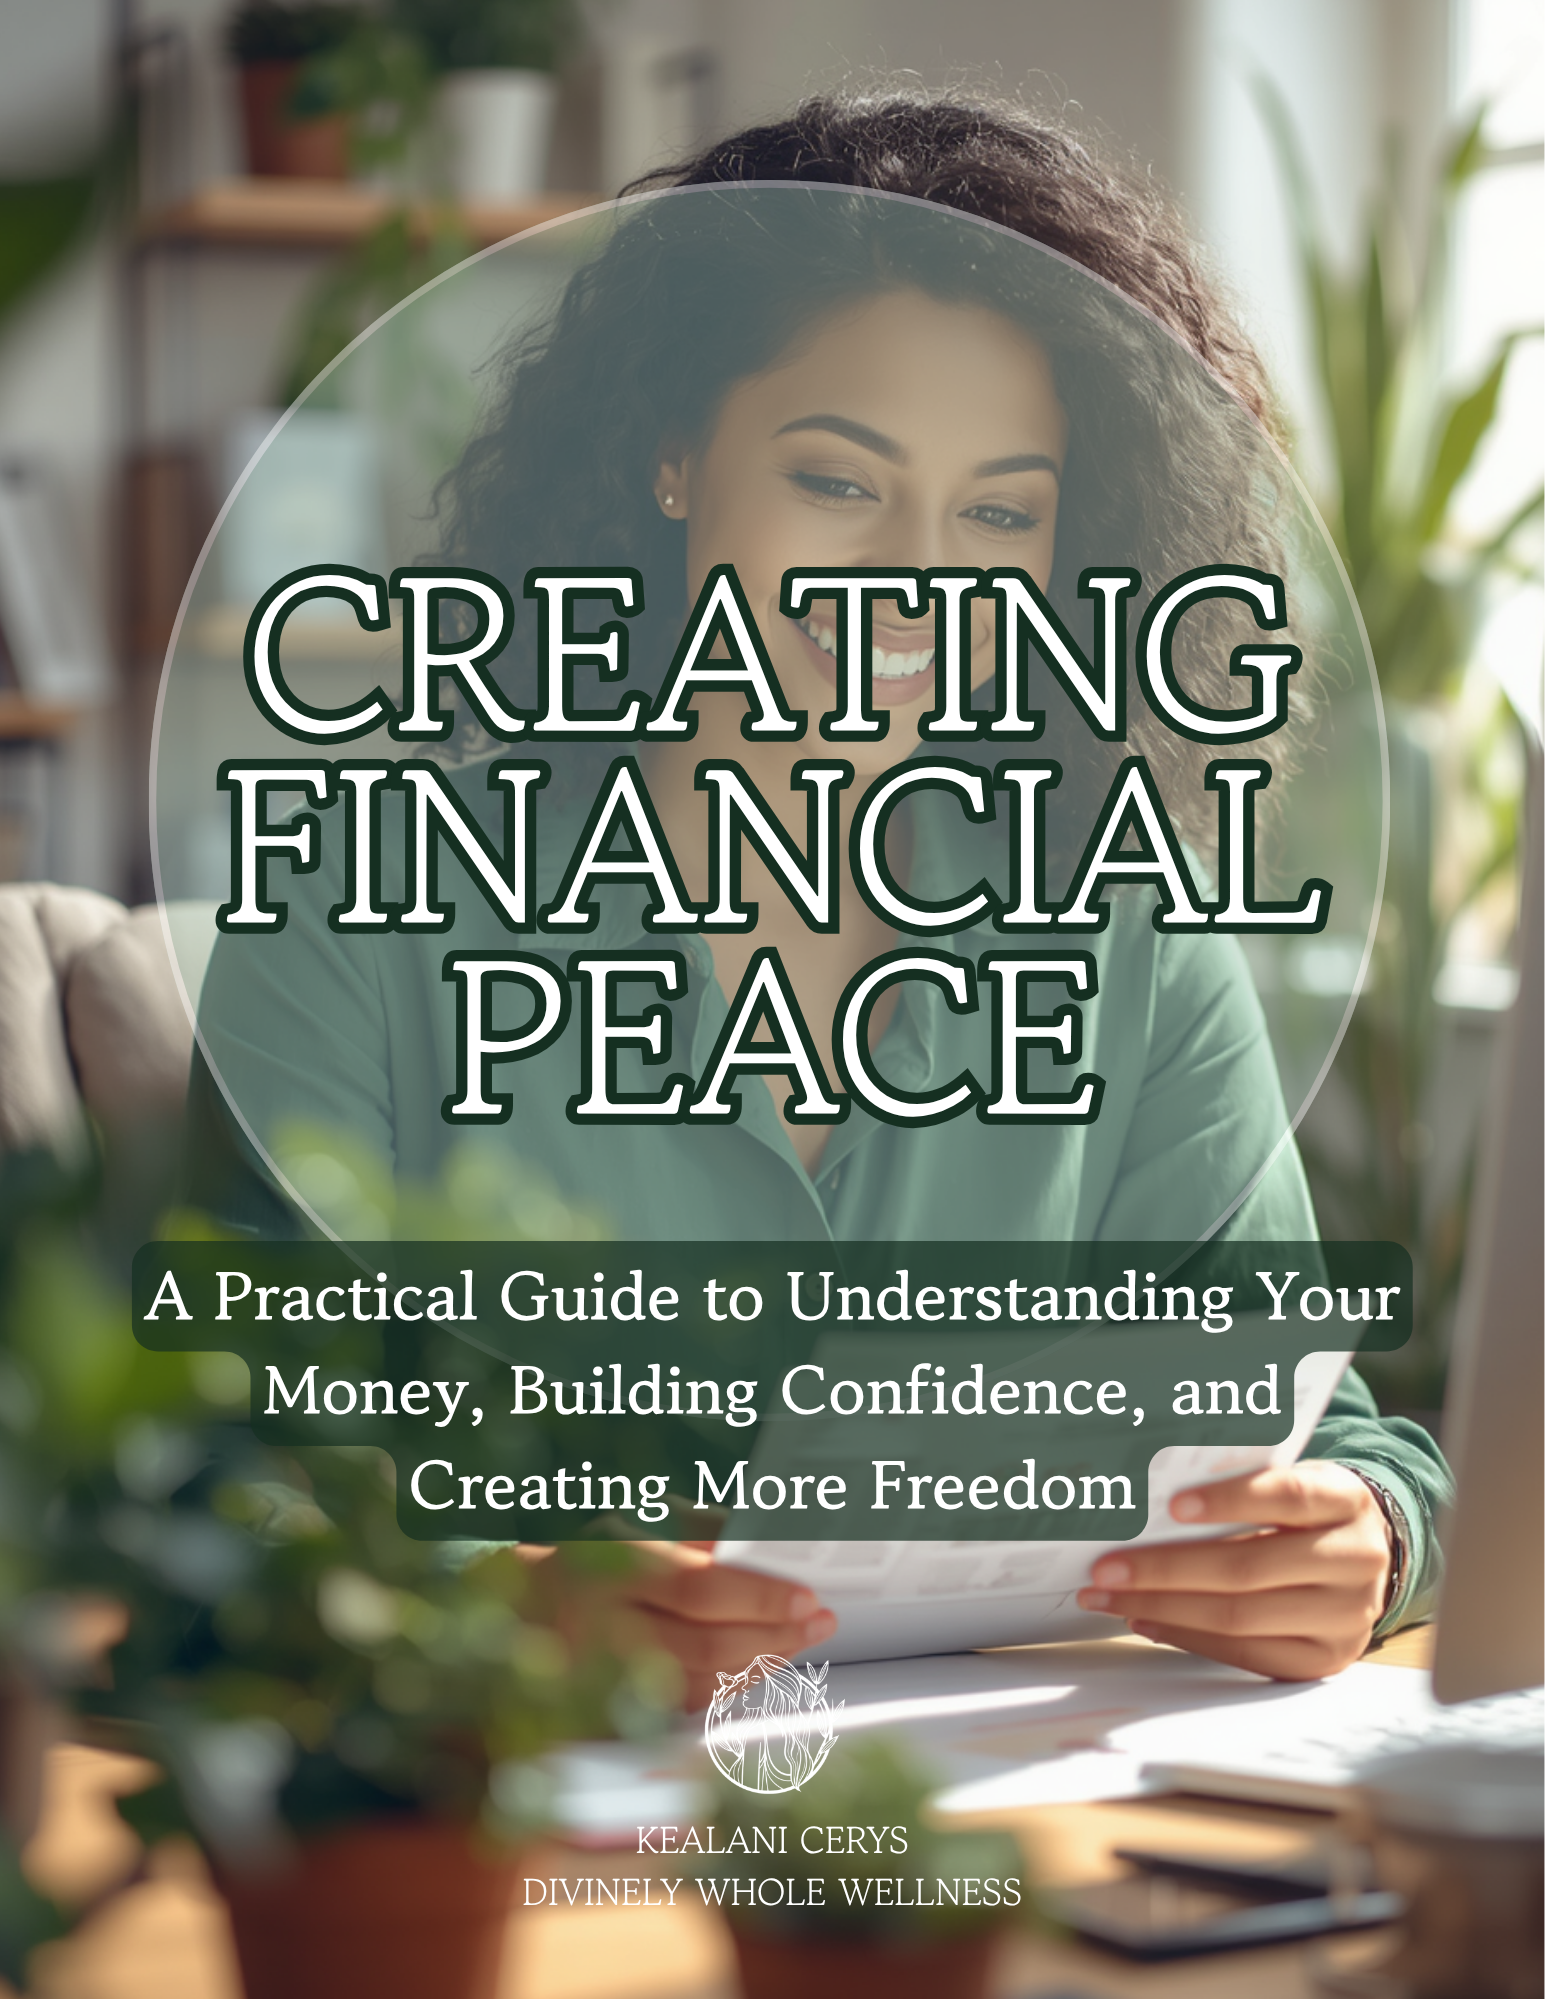
I’ve put together my own book of tips and information to help you create systems that work for your financial situation.
Creating Financial Peace is a practical guide and workbook for developing a more confident, intentional, and peaceful relationship with money. Explore the mindset and habits that shape your financial life while learning how to organize your finances, build savings, approach debt, increase your income, invest with greater confidence, and create a plan for the future you want.
Financial Disclaimer
A Note About Financial Information
The financial information I share is intended for general educational and informational purposes and is based on my personal experiences, habits, and perspectives. It is not intended to be individualized financial, investment, tax, legal, or accounting advice, and I am not a licensed financial advisor, tax professional, or attorney.Everyone's financial circumstances, goals, income, and needs are different. Before making significant financial, investment, tax, or debt-related decisions, consider doing your own research and consulting with an appropriately qualified professional who can take your individual situation into account.
My goal is simply to share what I've learned, encourage thoughtful conversations about financial wellness, and offer ideas that may help you become more informed and intentional about your own financial life.